
Blog
7 Ways Risk Tolerance Influences Business Insurance
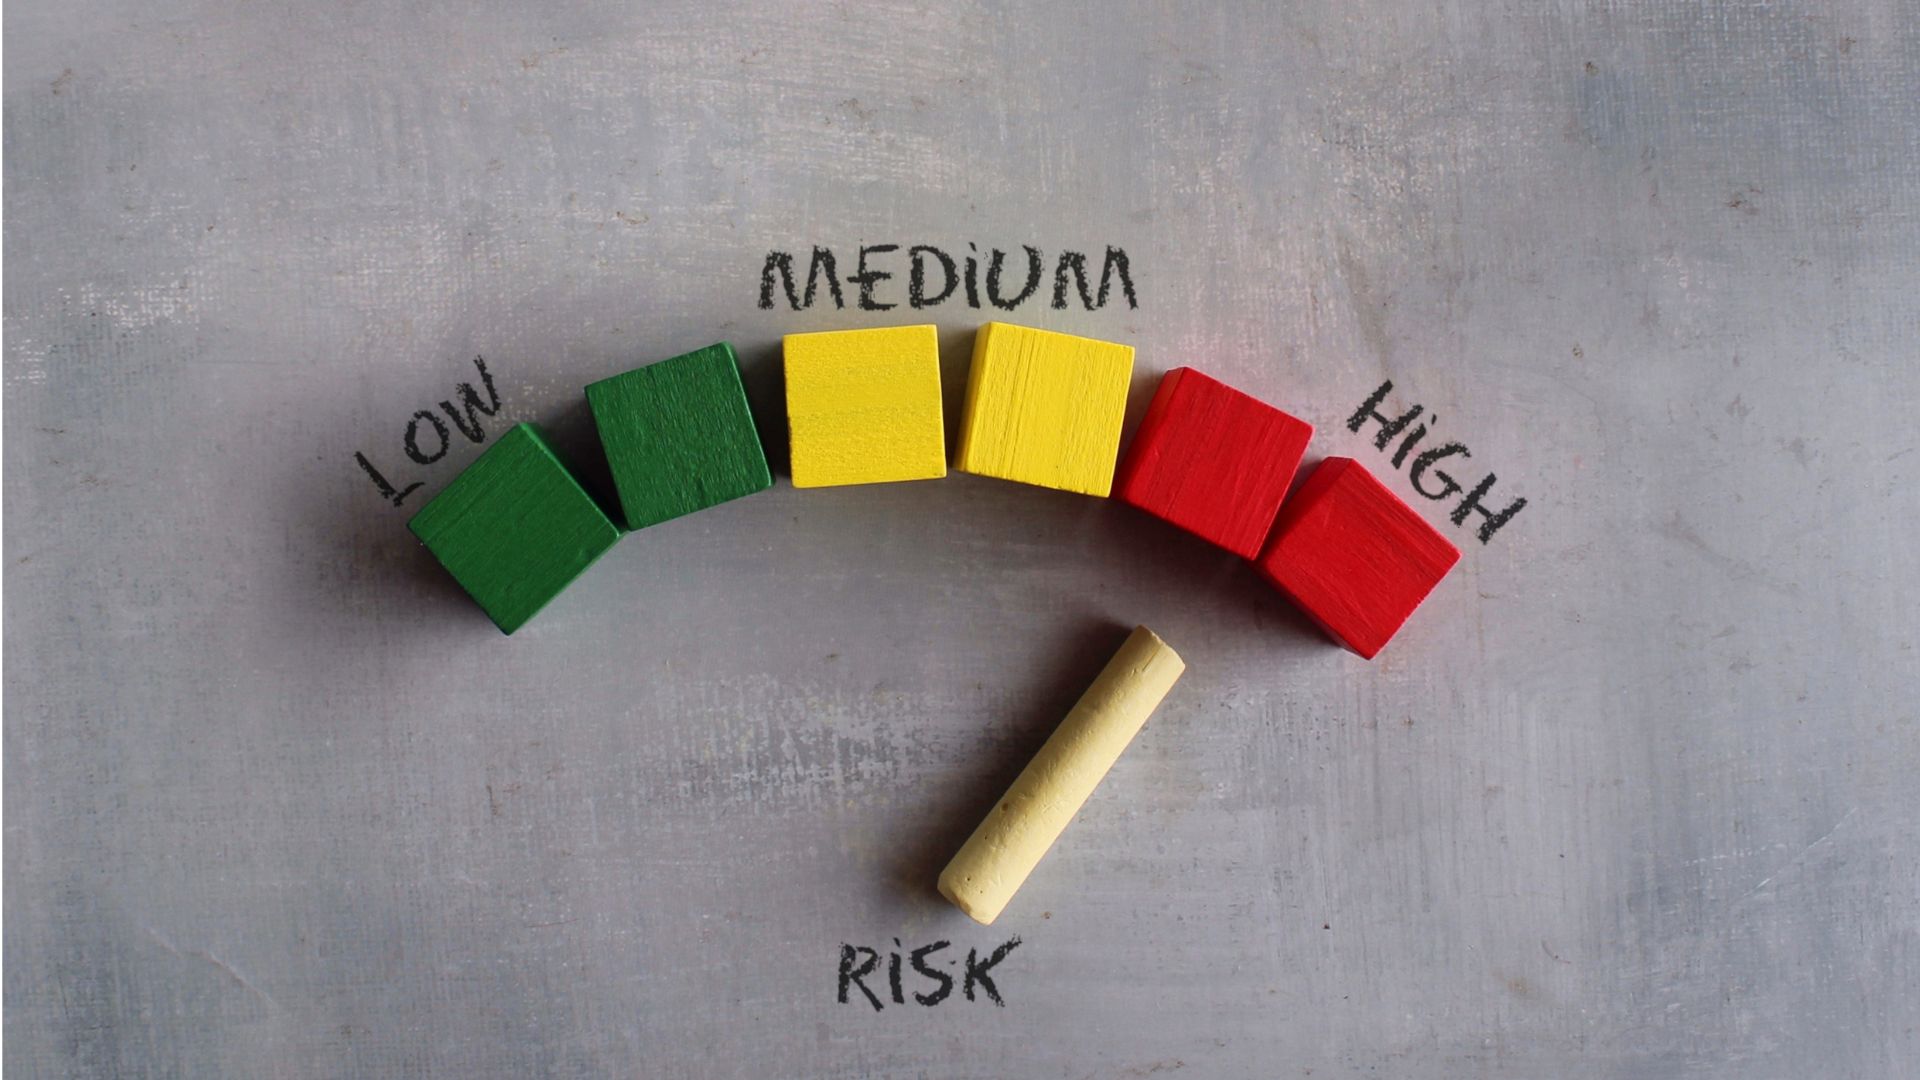
Most business owners treat insurance like a box to check. They buy it, renew it, and move on. But the way your company handles risk shapes nearly every part of your business insurance strategy, from deductibles to coverage limits.
Understanding risk tolerance is not a nice extra. It can be the difference between real protection and a policy that costs too much or leaves you exposed. Here are seven ways your comfort with risk can lead to better business insurance strategies.
-
It Determines How Much You Should Self-Fund
Every business keeps some losses on its own, whether it’s a broken machine or a minor vehicle claim. The real question is how much you should keep and how much you should transfer to an insurer. A company with strong cash reserves can often take a higher deductible and save on premium. A leaner business may struggle with that same deductible the first time a real claim lands. Your real cash cushion—not just the number on a quote—should guide the choice.
-
It Shapes Which Deductibles Make Sense
Many businesses pick deductibles because they lower the premium the most. But could they pay that deductible tomorrow without hurting operations? A risk management approach starts with your real financial capacity, not the sticker price. That usually leads to a better fit when a loss actually happens.
-
It Affects How You Put Coverage First
Not every risk matters the same way, and your risk tolerance should help you decide what to put first. A business that can handle a small property repair but would be hit hard by a big liability claim should usually put liability protection first. Getting that priority right means looking honestly at property and casualty exposure along with liability, cyber, and workers’ comp, instead of treating every line the same.
-
It Influences How Hard You Work on Loss Control
Businesses that keep more risk usually have a reason: they work to prevent losses in the first place. A strong loss control program cuts down small claims, which makes higher deductibles and more retained risk easier to handle. Prevention and retention work best together. The more you reduce losses, the more risk you can safely keep.
-
It Changes as Your Business Grows
What felt fine two years ago may not fit now. If your business has grown, opened a new site, or signed contracts with strict liability terms, your risk profile has changed. Your risk tolerance should be reviewed often, not locked in at the first renewal.
-
It Impacts Contract and Stakeholder Requirements
Sometimes your comfort with risk is only part of the picture. Landlords, lenders, and clients often set minimum coverage terms in contracts. That can push you toward more transfer than your finances alone would suggest. A good broker helps you balance what you can keep with what outside parties require, so you do not over insure where you do not need to.
-
It Shows When Your Setup Is Out of Sync
There are clear warning signs that your risk tolerance and your coverage no longer match. Cash flow strain every time a deductible hits. Delaying repairs to avoid paying out of pocket. Paying for very low deductibles even though your reserves could cover a routine loss. If any of that sounds familiar, your policy setup has not kept pace with where your business stands today.
Building a Strategy Around Your Real Comfort Level
Risk tolerance is not a one-time conversation. It should change as your business changes. Infinity Insurance Partners helps companies review financial capacity, set deductibles and limits that fit, and build business insurance strategies that protect against major loss without paying for more caution than the business needs.
If it has been a while since your coverage was reviewed against your company’s real financial position, request a consultation with Infinity Insurance Partners to see where adjustments could strengthen your strategy.
Frequently Asked Questions
Question: How do I figure out my business’s actual risk tolerance? Short answer: Start with cash reserves, revenue stability, and current debt or other financial obligations. That gives you a real number for what your business could absorb without disrupting operations.
Question: Should risk tolerance be the only factor in choosing deductibles? Short answer: No. Contract terms, industry norms, and stakeholder expectations matter too, along with what your finances can support.
Question: How often should I reassess my risk tolerance? Short answer: At least at every renewal, and again after major changes like fast growth, a new location, or new contract demands.
Question: Can loss control actually change how much risk I can retain? Short answer: Yes. Fewer small losses mean more room to raise deductibles or keep more risk without straining cash flow.
Question: What’s a warning sign that my coverage does not match my risk tolerance? Short answer: Frequent cash flow strain from deductibles, delayed repairs to avoid out-of-pocket costs, or paying for coverage that is far more cautious than your finances require.
Question: What does self-funding mean, and how do I decide how much to keep?
Short answer: Self-funding means paying for small, expected losses, including your deductible, from your own cash instead of sending them to the insurer. Look at cash reserves, revenue stability, and current obligations. If reserves are strong, a higher deductible can make sense and save premium. If cash is tight, a high deductible can create real strain when a claim hits.
Question: How should risk tolerance guide which deductible I choose?
Short answer: Start with what you could pay tomorrow without disrupting operations—not with the biggest premium discount. A deductible that matches your financial capacity is easier to live with. Pair that with a strong loss control program to reduce small claims and make higher deductibles more workable.
Question: How do I prioritize coverage types when I cannot optimize everything?
Short answer: Focus on the loss that would hurt your business the most. If you can handle a small property repair but a large liability claim would be devastating, put liability protection first and accept higher deductibles elsewhere. Review property and casualty exposure, liability, cyber, and workers’ comp together rather than treating each line the same.
Question: How do contracts and stakeholder requirements affect my ideal insurance structure?
Short answer: Landlords, lenders, and clients often require minimum limits or specific coverages, which can push you toward more risk transfer than your finances alone would call for. A good broker helps you meet those terms while staying close to your comfort level, so you do not overinsure.
Question: What are signs my coverage is out of sync with my current risk tolerance?
Short answer: Red flags include cash flow strain every time a deductible hits, delaying repairs to avoid out-of-pocket costs, and paying for very low deductibles even though your reserves could handle routine losses. Those signs suggest your policy structure has not kept up with your current financial position and comfort with uncertainty.
Latest Posts

Commercial Dispute Funding: Key Considerations for Business Owners
Learn about commercial litigation funding, its financial implications, and important considerations for businesses navigating legal disputes.

How Property Damage Exposes Businesses to Financial Loss
Explore how property valuations, coverage limitations, and business interruption can affect a company’s financial resilience after a major loss.
Negligence and Its Impact on Commercial Liability
Learn how negligence claims arise, how commercial liability insurance responds, and how to align limits with real exposure before renewal.