
Blog
Equipment Breakdown Coverage and the Business Risks It Can Help Address
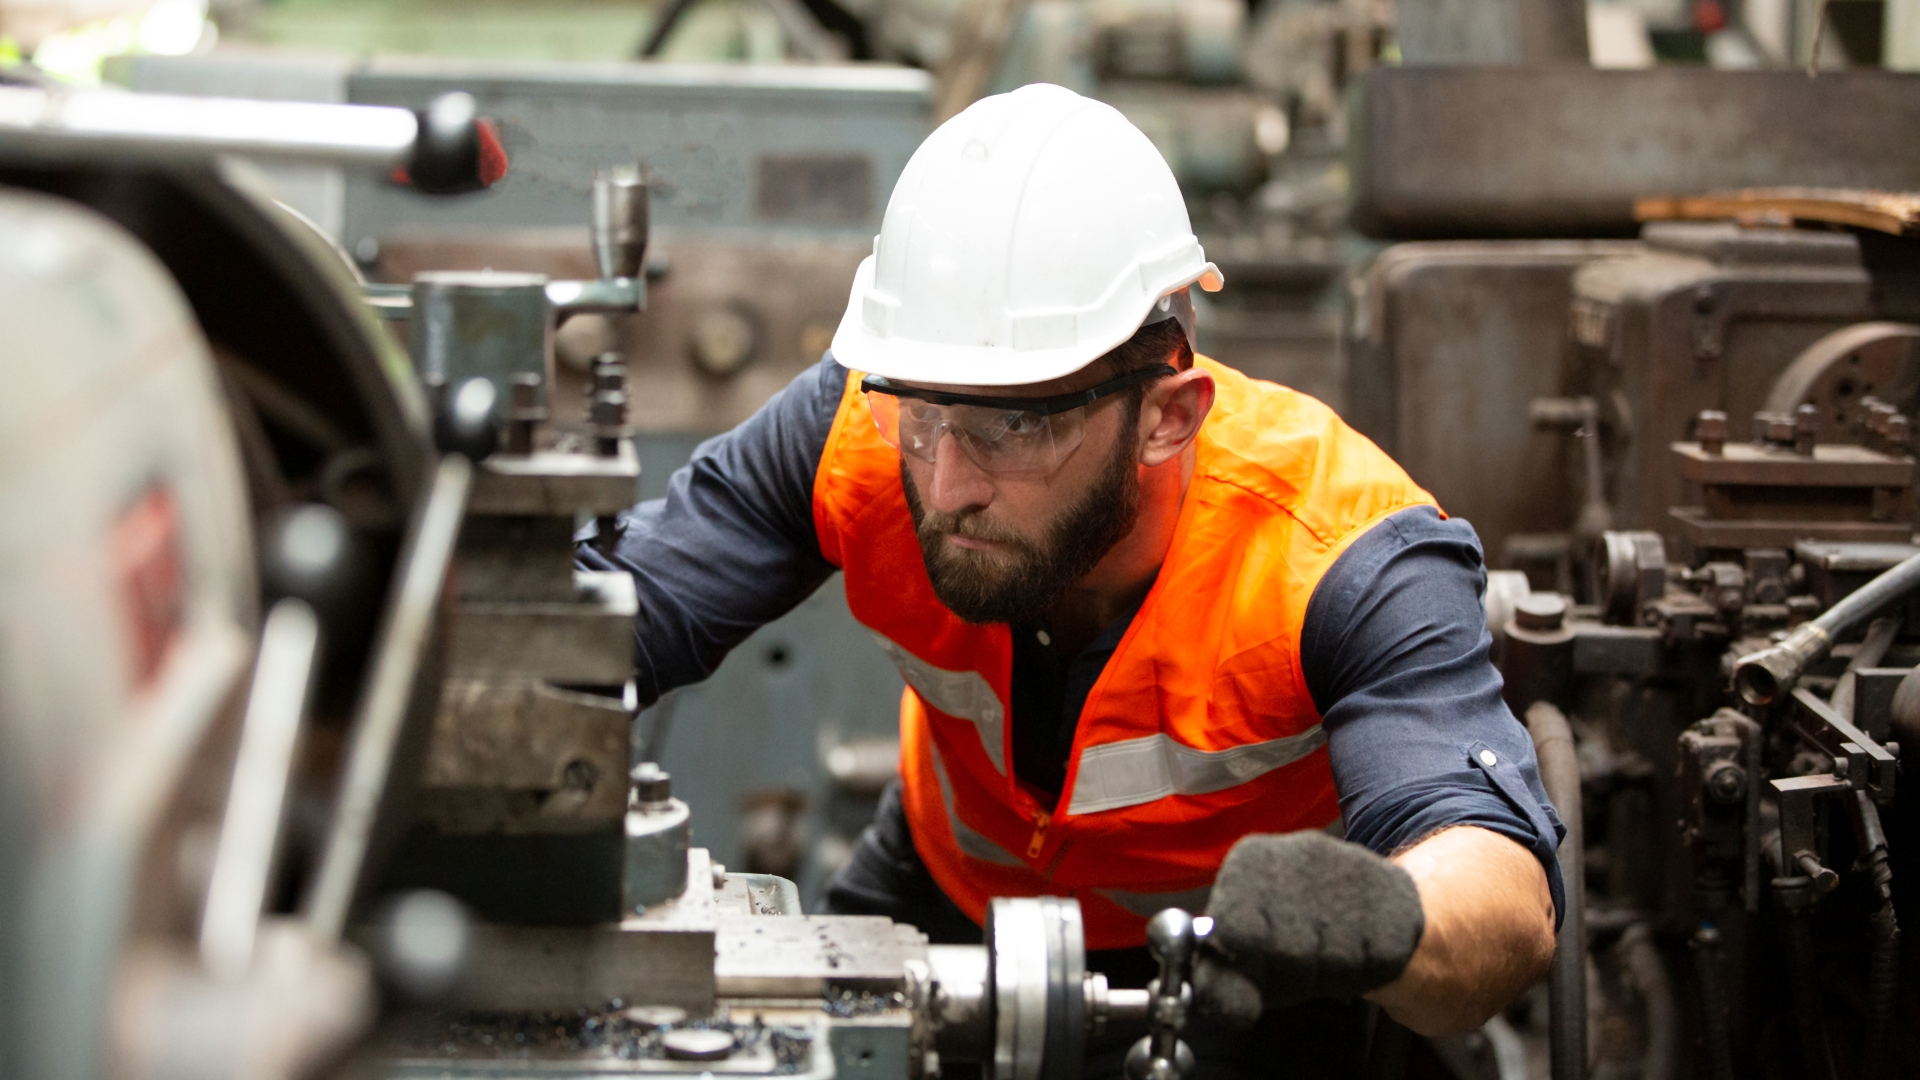
Most businesses run on equipment they rarely think about until it stops working. HVAC systems, refrigeration units, servers, production line machinery, boilers, electrical panels — these assets quietly keep operations moving, and their failure rarely announces itself in advance. A single mechanical or electrical breakdown can halt production, spoil inventory, or shut down a location entirely, often with far more financial impact than the repair bill itself suggests. That’s the gap Equipment Breakdown Coverage is designed to help close.
Why Equipment Failures Create More Than a Repair Bill
Standard commercial property policies are typically built around named perils like fire, wind, or theft — not the sudden mechanical or electrical failure of equipment. That distinction matters. A motor that burns out, a boiler that cracks under pressure, or a control panel that short-circuits usually isn’t the result of an external event; it’s an internal breakdown, and many property forms exclude it outright or limit it significantly.
For a business owner, that exclusion can be an expensive surprise. Replacing a commercial refrigeration compressor, restarting a production line after an electrical failure, or repairing HVAC systems in a multi-tenant building involves not just equipment costs, but lost income, spoiled product, and sometimes contractual penalties for missed deadlines.
What This Type of Coverage Typically Addresses
Coverage in this category is generally built around a few core exposures:
- Repair or replacement costs for equipment damaged by mechanical breakdown, electrical arcing, or motor burnout
- Business income loss resulting from downtime while equipment is repaired or replaced
- Spoilage of perishable goods tied to refrigeration or temperature-controlled equipment failure
- Extra expense coverage for costs incurred to keep operations running during repairs, such as temporary equipment rental
The specific scope varies by policy and industry, which is why this protection is worth reviewing against the actual assets a business depends on, rather than assumed as part of a standard property package.
The Business Risks Behind a Single Mechanical Failure
The risk isn’t limited to manufacturers or facilities with heavy machinery. Restaurants depend on refrigeration and kitchen equipment. Office buildings rely on HVAC and elevator systems. Medical practices depend on diagnostic and sterilization equipment. Retailers depend on point-of-sale systems and climate control. In each case, a mechanical or electrical failure can interrupt the core function of the business, not just damage a piece of property.
This is where the exposure often gets underestimated. Owners tend to budget for equipment maintenance and eventual replacement, but fewer account for the income disruption that follows an unplanned failure — the days or weeks a business may operate at reduced capacity, or not at all, while repairs are underway. Business interruption exposure tied to equipment failure deserves the same scrutiny as exposure tied to fire or storm damage.
Where This Coverage Fits Into a Broader Risk Strategy
This exposure shouldn’t be evaluated in isolation. It connects directly to property coverage, business income planning, and even liability exposure if failed equipment causes harm to employees, customers, or a leased space. A comprehensive review typically looks at:
- Which equipment is critical to daily operations and what its age and maintenance history look like
- How long the business could realistically operate, or absorb lost revenue, if that equipment failed tomorrow
- Whether current property coverage explicitly includes or excludes mechanical and electrical breakdown
- How lease agreements or vendor contracts allocate responsibility for equipment tied to a facility
Businesses that treat this as part of an ongoing risk management conversation, rather than a one-time policy purchase, tend to catch gaps before a claim forces the issue. Equipment ages, operations expand, and new machinery gets added — each change is a reason to revisit whether coverage still matches what’s actually at stake.
Practical Steps Business Owners Can Take
- Inventory the equipment most critical to daily operations, including age and maintenance records
- Confirm whether current property coverage addresses mechanical and electrical breakdown, or excludes it
- Estimate the realistic downtime and income impact of a major piece of equipment failing without warning
- Revisit coverage whenever new equipment is purchased, financed, or leased
- Build equipment condition reviews into regular maintenance schedules, not just insurance renewals
None of this requires overhauling how a business operates day to day. It simply means treating equipment reliability as a financial exposure worth planning for, not an assumption.
How Infinity Insurance Partners Can Help
Equipment failures don’t wait for a convenient time, and the businesses that recover fastest are usually the ones that reviewed their exposure before it became a claim. Infinity Insurance Partners works with business owners to evaluate where mechanical and electrical breakdown risk intersects with property, business income, and liability coverage, helping build a program that reflects the equipment a business actually depends on rather than a generic policy template. Our team takes a consultative approach, working through the specific machinery, systems, and operational realities that make each business different.
If your business relies on equipment that would be costly to lose even for a few days, it’s worth a closer look at how your current program handles that risk. Contact our team to review your coverage before a breakdown forces the conversation.
Q&A
Question: What’s the difference between property insurance and coverage for equipment failure? Short answer: Standard property policies generally respond to external perils like fire or storms, while mechanical and electrical breakdown is often excluded or limited unless addressed specifically.
Question: What kinds of equipment are typically covered? Short answer: Coverage can extend to HVAC systems, refrigeration units, boilers, electrical panels, production machinery, and other equipment critical to daily operations, depending on the policy.
Question: Does this type of coverage help with lost income, not just repairs? Short answer: Many policies include business income and extra expense provisions to help offset revenue lost while equipment is being repaired or replaced.
Question: How often should a business review this exposure? Short answer: At least annually, and any time new equipment is purchased, leased, or added to a facility, since aging or expanding equipment changes the risk profile.
Latest Posts

How Property Damage Exposes Businesses to Financial Loss
Explore how property valuations, coverage limitations, and business interruption can affect a company’s financial resilience after a major loss.
Negligence and Its Impact on Commercial Liability
Learn how negligence claims arise, how commercial liability insurance responds, and how to align limits with real exposure before renewal.
Risk Financing Strategies for Smarter Business Protection
Learn how businesses balance insurance costs, retained losses, and financial protection.